Quick answer: After you file a hail roof claim, your insurance company sends an adjuster to inspect the roof and write an estimate. They look for hail hits on the shingles, damage to soft metals like vents and gutters, and signs the damage came from this storm rather than age or wear. To prepare, get your own contractor inspection first, document the storm date and damage with photos, and have your contractor at the adjuster meeting so the damage gets found and measured correctly.
Need it done? See our hail damage roof repair service in Longmont and across the Front Range, or call 720-828-7997.
Who the Adjuster Is
The adjuster works for the insurance company, either as a staff adjuster or an independent adjuster hired for storm season. Their job is to decide whether the damage is covered and what it costs to fix under your policy. They are not your advocate. After a big Front Range storm, adjusters may be handling dozens of claims a week, which is why damage gets missed.
What a Hail Roof Claim Adjuster Checks
- Test squares. Adjusters commonly mark off a 10-by-10-foot area on each slope and count the hail hits inside it. Too few hits per square can mean a repair instead of a replacement.
- Hail hits on shingles. Soft spots, cracked or bruised mat and granules knocked loose in round marks.
- Collateral damage. Dents in roof vents, flashing, gutters, downspouts, AC fins and window screens. These help prove the size and direction of the hail.
- Storm date. Whether the damage matches a recorded hail event on or near the date you reported.
- Age and wear. Blistering, cracking and granule loss from age are not covered, so adjusters look for reasons to call damage wear and tear.
- Other roof parts. Skylights, ridge cap, chimney flashing and pipe boots.
How to Prepare for the Adjuster Visit
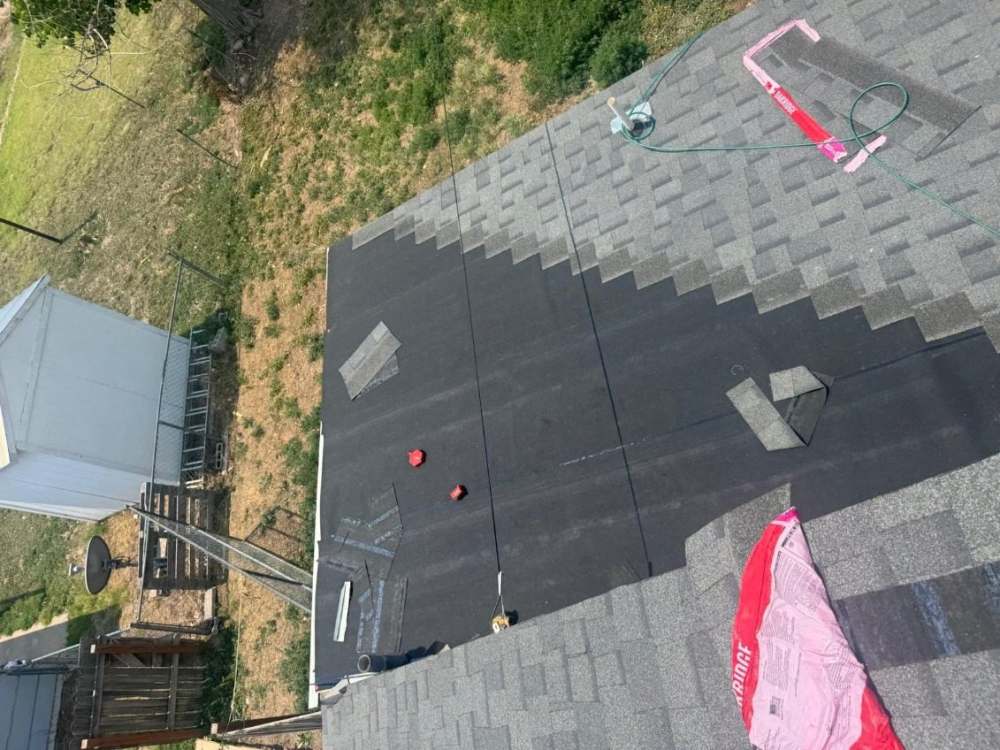
- Get a contractor inspection before the adjuster comes. You will know what damage is there and won’t rely only on the insurer’s count. Here is why to call a contractor first.
- Write down the storm date and time, and save any local news or weather reports about it.
- Photograph the damage from the ground: dented gutters, downspouts, AC unit, window screens, siding and any shingle granules in the downspouts.
- Have your contractor attend. Under Colorado law, a contractor you have a contract with can discuss the scope of repairs with your insurer.
- Be there yourself, and ask the adjuster to show you what they found and how many hits they counted on each slope.
- Ask for a copy of the estimate and the inspection photos.
What Often Gets Left Off the First Estimate
First estimates are often short. Common missing items on Colorado roof claims include:
- Drip edge, ice-and-water barrier and other code upgrades the building department requires.
- Starter strip, ridge cap and hip shingles.
- Steep-slope or high-roof charges, and a second layer tear-off.
- Vents, pipe jacks and flashing that need to be replaced, not reused.
- Permit fees and dump fees.
- Gutters, downspouts and window screens damaged in the same storm.
Your contractor adds missing items through a supplement, with measurements and photos to back them up.
If Your Claim Is Denied or Comes Back Low
- Ask for the reason in writing, along with the adjuster’s photos and notes.
- Request a re-inspection with your contractor present. A second adjuster often finds damage the first one missed.
- Check for a cosmetic damage exclusion, which can exclude dents in metal roofing that do not let water in.
- Look at the appraisal clause in your policy if you and the insurer agree damage is covered but disagree on the amount.
- Consider a licensed public adjuster for large or complicated claims. In Colorado, a roofing contractor cannot act as your public adjuster.
- File a complaint with the Colorado Division of Insurance if the insurer is not responding.
Colorado Rules That Protect You
- A roofing contractor cannot pay, waive or rebate your deductible. Anyone offering a “free roof” is breaking the law.
- A roofing contractor cannot claim to be or act as a public adjuster, but can discuss the repair scope with your insurer if you have a contract with them.
- Most policies pay actual cash value first and the rest after the work is done. Your policy sets the deadline to finish the work and collect it, so read that section. See ACV vs. RCV explained.
Hail Roof Claim Adjuster Day Checklist
- Your claim number and the storm date.
- Dated photos of the roof, gutters, vents, siding, window screens and anything hail hit on the ground, like cars or patio furniture.
- Your contractor’s inspection notes with the damage marked on each slope.
- Interior photos of any leaks or ceiling stains.
- The age of the roof and any past repair records.
- Your contractor on site, so both people walk the roof together.
What Happens After the Adjuster Visit
- The estimate arrives. It lists what the insurer will pay for, line by line.
- Compare it with your contractor’s scope. Look for missed slopes, missing drip edge, ice barrier, vents, flashing and gutters.
- Ask for a supplement if items are missing. Read what a roof supplement is.
- The first check is often depreciated. Replacement cost policies usually release the held-back amount after the work is done. See ACV vs. RCV.
- The work is scheduled, and your contractor sends final invoices to close out the claim.
Our insurance claim help page explains how we work with your adjuster. Siding hit too? Read hail damage siding repair: repair vs. replace.
Frequently Asked Questions
Should I have a contractor at the insurance adjuster inspection?
Yes. A contractor who knows hail damage can point out hits and damaged parts the adjuster might miss. Under Colorado law, a contractor you have a contract with can discuss the repair scope with your insurer.
How many hail hits does an adjuster need to approve a roof replacement?
It varies by insurer. Many adjusters count hits in a 10-by-10-foot test square on each slope, and too few can mean a repair instead of a replacement.
Can I get a second adjuster if I disagree with the first one?
You can ask for a re-inspection. Insurers often send a different adjuster, especially when your contractor has documented damage the first inspection missed.
What if the adjuster says my roof damage is just wear and tear?
Ask for the reason in writing, get an independent contractor inspection, and request a re-inspection with photos of the hail hits and dented metals that show storm damage.
Can my roofer act as my public adjuster in Colorado?
No. Colorado law bars roofing contractors from acting as public adjusters. A licensed public adjuster can represent you, and your contractor can still discuss the repair scope with the insurer.
What should I have ready for the hail roof claim adjuster?
Your claim number, the storm date, dated photos of the roof and other hail damage, your contractor’s inspection notes, interior leak photos and the roof’s age. Have your contractor there too.
What happens after the roof adjuster leaves?
The insurer sends a line-by-line estimate. Compare it with your contractor’s scope, and ask for a supplement if items like drip edge, vents or flashing are missing.
Get an Honest Inspection Before the Adjuster Comes
We only install Class 4 impact-resistant shingles (Owens Corning Duration STORM or better) with all new metals and flashing, and we tell you honestly if your roof isn’t worth a claim. Josh Brooks Construction and Renovation Inc. is a licensed general contractor based in Longmont with 30 years in construction, serving 46+ Front Range cities. Call 720-828-7997 or text 720-453-5095.
Licensed. Local. Not a storm chaser.
Sources
- C.R.S. 6-22-105: Roofing contractor deductible and public adjuster rules
- United Policyholders: Colorado Homeowners Insurance Reform Act of 2013
- United Policyholders: Hail loss claim guidance
Colorado hail & insurance: by the numbers (2026)
- Colorado ranks #2 in the U.S. for hail insurance claims, behind only Texas.
- The Front Range sits in “Hail Alley,” the highest frequency of large hail in North America — about 7–9 hail days a year.
- A Colorado state analysis (Feb 2026) found hail is 26–54% of the homeowners premium depending on county — roughly 50% along the Front Range.
- The average Colorado premium hit about $6,630 in 2026, up ~100.8% since 2020 — the largest increase of any state.
- Colorado typically sees 3–4 catastrophic hailstorms a year (each ≥ $25M in insured damage); severe season runs mid-April to mid-September.
Sources: Rocky Mountain Insurance Information Association (RMIIA); Colorado Division of Insurance (Feb 2026); National Weather Service; NAIC / Insurify (2026).
Go deeper:


